Quick digital process
See your options, choose your terms, and close online. Fast and simple. No in-person meetings.
Pay off credit card debt, cover the unexpected, or fund what's next with a home equity line of credit. No weeks of waiting. Get pre-approved in five minutes.1
No credit impact.2 Zero obligation.
Why get a HELOC with Kin
Personal loans, credit cards — we know you've got options. Some are slower, cost more, or make you refinance a mortgage you don't want to touch. A Kin HELOC lets you access the cash you need, when you need it, from a company you already trust to protect your home.
See your options, choose your terms, and close online. Fast and simple. No in-person meetings.
Credit cards & personal loans can charge 1.5–3x more in interest.* Save big on the same balance.
Life happens. That's what a HELOC is for. Pay it down. Draw again, up to 100% of the amount.
*Based on national averages as of 2026: credit cards run about 20–24% APR, HELOCs about 7–8% (CBS News, Bankrate, Federal Reserve). Personal loan rates vary widely, from about 12–18% depending on lender and credit profile. Individual rates vary.
Kin vs. the bank
| Feature | Kin HELOC | Bank HELOC |
|---|---|---|
| Time to approval | As little as 5 minutes1 | 1–2 weeks |
| Time to funding | As little as 5 days1 | 30–45 days |
| Credit check to see your options | No impact on your score (soft pull)2 | Often affects your score (hard pull) |
| Paperwork | Online application | Statements and W-2s, submitted in person |
| Closing | Remote online notary | Branch visit |
| Redraw | Up to 100% of your line | Varies, often capped |
Bank timelines reflect typical industry ranges for home equity lines of credit, not any specific lender. Your timeline depends on your property and how quickly verification clears.
Flexible funding
Open one line of credit; unlock countless ways to use your funds. Here are some of the most common.
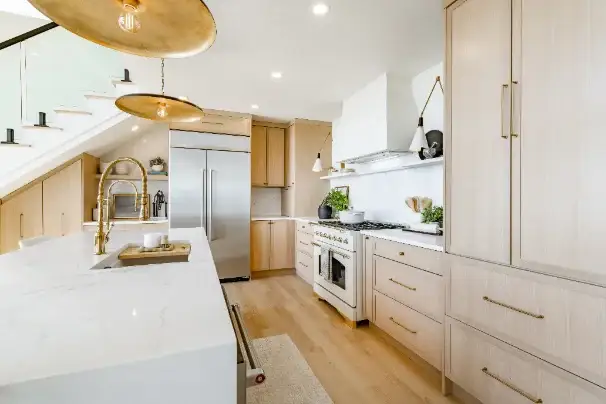
Make upgrades that add real value: a new roof, impact-resistant windows, or the kitchen you always wanted.
Trade high-interest credit card and personal loan debt for one affordable monthly payment.
When it matters most, you can't afford to wait weeks. Have a safety net ready for whatever comes your way.
Get cash for copays, coinsurance, deductibles, and other expenses that insurance doesn't cover.
Cover tuition, room and board, or the gap financial aid doesn't close, like a semester abroad.
Quick access to cash means you can make a deposit on an investment property — before the competition.
How it works
It only takes five minutes to see real financing options, and it won't affect your score.1, 2
Choose your rate and repayment term. Then close with our online notary.
Access funds in as little as five days.1 Then draw again as expenses come up.
Kin helps you cover your home — and access its equity
Kin is committed to making life simpler, more affordable, and better for Florida homeowners. That means offering a suite of products that serve your needs — and your wallet.
Home equity lending: Access your equity without changing your mortgage rate.
Purchase loans: Work with Kin to get pre-approved quickly and into your new home.
Homeowners insurance: Get coverage that's built for Florida and save an average of $1,058/year3 when you switch.
Auto insurance: Add auto to your home insurance policy and you could save on both with our auto bundle discount.
Property tax appeal: Your county's value sets your property tax bill, and it may be too high. We file the appeal. You keep every dollar you save.
Have a question we didn't answer? Call us at (888) 610-8206.
A home equity line of credit (HELOC) is a revolving credit line that allows you to borrow against the value of your property. It functions similarly to a credit card, where you are given a specific limit and can use as much or as little as you need. This limit is determined by your equity, which is the difference between your home's current market value and the amount you still owe on your mortgage.
During the initial "draw period" — which typically lasts 10 years — you can borrow as much or as little as you need, up to your approved credit limit, paying back only the interest on the amount you actually use. Because HELOCs usually come with variable interest rates, your monthly payments may fluctuate based on market conditions. Once the draw period ends, you enter the repayment phase. At this stage, you can no longer withdraw funds and must begin paying back both the principal and interest. It is essential to remember that your home secures the loan, so failing to make payments would put you at risk of foreclosure.
While both options let you tap into your home's value, they work in very different ways. A home equity loan is essentially a second mortgage. You get all the money in one big chunk right at the start. Most of these loans come with a fixed interest rate, so your monthly payment stays the same until the balance is gone. It's a straightforward path for people who have a specific, one-time cost and want the peace of mind that comes with a predictable bill.
A HELOC is a bit more like a credit card. Instead of taking all the cash at once, you get access to a line of credit that you can use as needed. You only pay interest on the amount you actually spend, not the full limit you were approved for. These may either have fixed or variable interest rates. Because you can borrow, pay it back, and borrow again, it offers a level of flexibility that a standard loan doesn't have.
A HELOC gives you a lot of freedom, but most homeowners use it for major life expenses or home improvements. Since you can draw from the line of credit as needed, it's a popular choice for long-term renovations like remodeling a kitchen or finishing a basement. These projects often have shifting costs, and a HELOC lets you pay contractors as the work progresses rather than all at once.
Beyond home upgrades, people often use HELOCs to consolidate high-interest debt or cover large, unpredictable bills. This could include anything from college tuition to medical expenses. But it's important to keep in mind that your home is the collateral. While you can technically use the money for "nice-to-haves" like a vacation or a new car, most experts advise against it.
How much you can borrow mainly depends on how much your home is worth and how much you still owe on your mortgage. Most lenders use a formula called the "combined loan-to-value ratio" to set your limit. Generally, lenders will let you borrow 80% to 85% of your home's total value, including your current mortgage.
For example, if your home is worth $400,000 and your lender has an 85% limit, they'll allow your total debt to reach $340,000. So if you still owe $250,000 on your mortgage, you could qualify for a line of credit up to $90,000. Just keep in mind that your credit score and monthly income also play a role. If your debt-to-income ratio is too high — usually over 43% — a lender might offer you a smaller amount to make sure you can comfortably handle the monthly payments.
It varies depending on the financial institution. However, most banks and credit unions look for a credit score of at least 620 to 660. If your score falls in this range, you can likely get your foot in the door, but you might face higher interest rates. If you're hunting for the best possible interest rates, you'll usually need a score of 740 or higher.
To qualify for a HELOC, most lenders require you to have at least 15% to 20% equity in your home. You calculate equity by taking your home's current market value and subtracting what you still owe on your mortgage. For instance, if your home is worth $400,000 and you owe $300,000, you have $100,000 — or 25% — equity.
A home equity loan is best when you have a specific, one-time expense and want the security of a fixed monthly bill. However, because you're using your home as collateral, you should only move forward if you have a stable income and a clear plan to meet the monthly payments for the full life of the loan.